




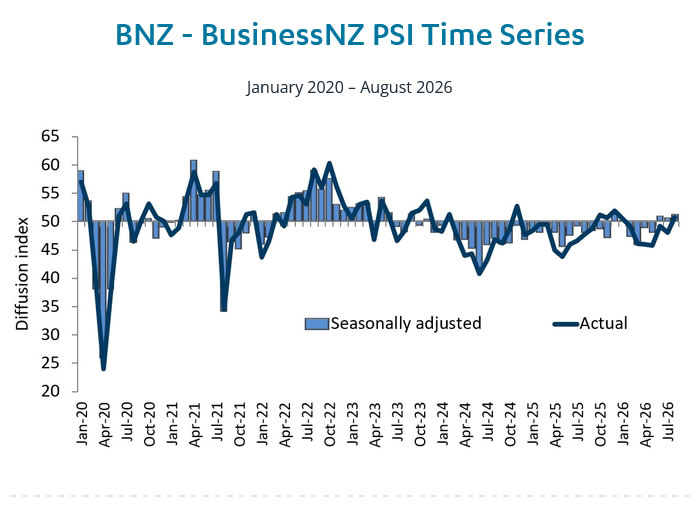
New Zealand’s services sector expanded for a third consecutive month in August, with the BNZ–BusinessNZ Performance of Services Index rising from 50.6 to 51.2. This level surpassed June’s 50.9 and matched the reading recorded in December 2025, marking the strongest performance since September 2023. The three‑month moving average increased to 50.9, its highest point since July 2023.
The overall figure masks a mixed picture. New orders and business activity accelerated, climbing from 52.8 to 55.2, providing the clearest signal that demand could strengthen further. By contrast, the activity/sales sub‑index slipped from 50.4 to 49.4, remaining below the expansion threshold, while employment nudged up from 48.5 to 49.4 but still signalled contraction. Stocks/inventories eased slightly to 50.8, and supplier deliveries improved modestly to 49.0. Only two of the five sub‑indices posted expansion readings.
BusinessNZ Chief Executive Katherine Rich described the recovery as fragile, noting that most components have yet to return to expansion. Sentiment among respondents weakened, with 60.8 % of comments expressing negativity amid concerns about living costs, interest rates and election uncertainty. BNZ Senior Economist Doug Steel said the rising three‑month average offers some confidence of an upward trend, but the divergence between stronger orders and sluggish current activity indicates that a robust services recovery has not yet taken hold.
Data Summary
Indicator
August
July
BNZ–BusinessNZ PSI
51.2
50.6
New Orders/Business
55.2
52.8
Stocks/Inventories
50.8
51.7
Employment
49.4
48.5
Activity/Sales
49.4
50.4
Supplier Deliveries
49.0
48.4
Key Takeaways
- New Zealand’s services sector expanded for a third consecutive month, with the PSI rising from 50.6 to 51.2.
- New orders and business activity showed the strongest momentum, accelerating from 52.8 to 55.2.
- Activity/sales fell below the 50‑point threshold, while employment and supplier deliveries also remained in contraction.
- Only two of the five component indices indicated expansion, highlighting a narrow‑based recovery.
- Negative sentiment increased to 60.8 % of responses, reflecting concerns about living costs, interest rates and election uncertainty.
- The rising three‑month average supports an improving trend, yet stronger orders have not yet translated into broader activity and hiring gains.