



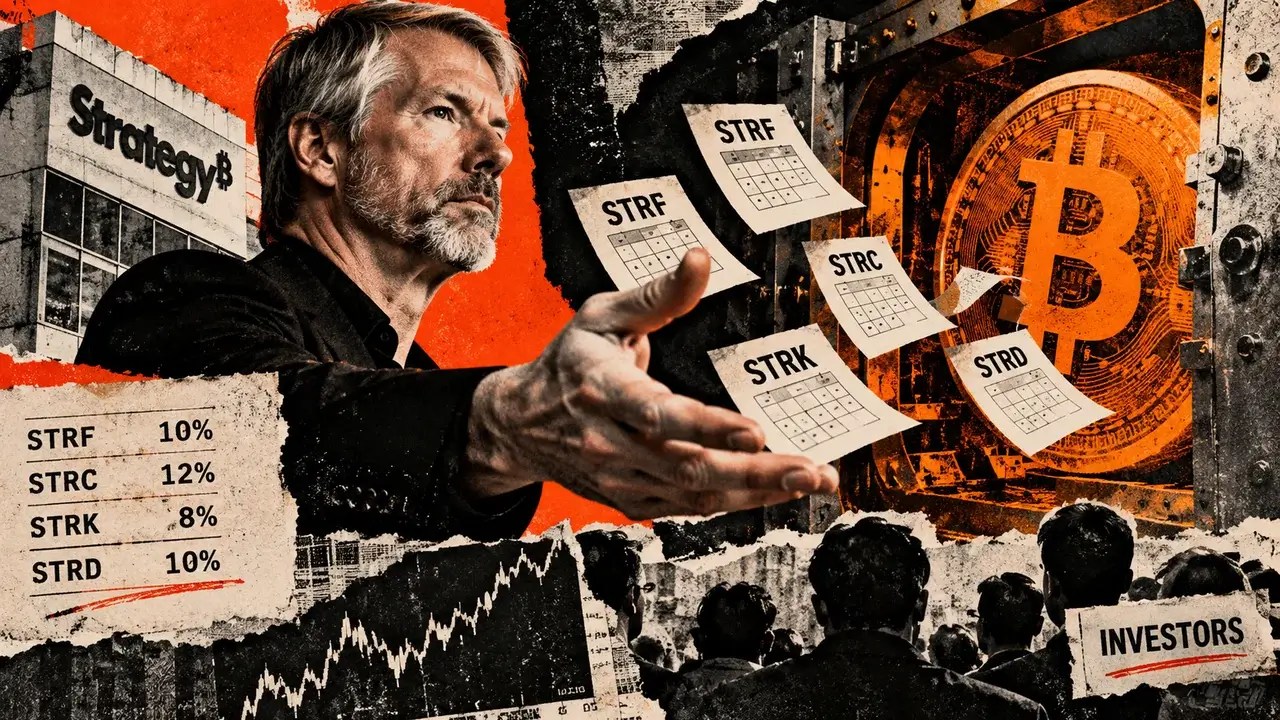
The @saylor account announced on Friday that Strategy aims to pay dividends daily on four preferred shares used in its Bitcoin financing strategy. The proposal would deliver cash to holders more quickly without altering the securities’ underlying economics at current rates. Its practical benefit to Strategy hinges on whether investors value the accelerated timing enough to pay a premium.
The pricing hurdle varies across the four series. Before the proposal, STRF traded above $100 at Thursday’s close, STRC hovered near that level, and STRK and STRD sat in the low $70s. These figures serve as a trading baseline, not proof that daily payments will boost demand or that Strategy could issue new shares at equivalent prices.
The post indicates dividends on STRF, STRC, STRK, and STRD would accrue every calendar day, including weekends and holidays, with payment the next business day. It did not specify daily record dates, an effective date, or series-by-series approvals. Strategy’s existing August 31 declaration maintains quarterly payments for STRF, STRK, and STRD and twice-monthly payments for STRC.
A faster calendar does not equal the same claim
Strategy’s preferred-stock disclosure distinguishes itself from mere payment frequency. Dividends on STRF, STRC, and STRK are cumulative, meaning unpaid amounts accrue under their terms. STRD’s dividends are noncumulative: an omitted regular payment does not create an arrears claim. All four series remain subject to board declaration and legally available funds, and STRK may pay a declared dividend in cash, MSTR shares, or both.
| Security | Current payment cadence | Annual dividend rate | Sept. 24 close | Sept. 24 volume |
|---|---|---|---|---|
| STRF | Quarterly | 10%; cumulative | $103.28 | 20,313 shares |
| STRC | Twice monthly | 12% at latest declaration; variable and cumulative | $98.28 | 1,023,834 shares |
| STRK | Quarterly | 8%; cumulative | $73.59 | 69,162 shares |
| STRD | Quarterly | 10%; noncumulative | $72.10 | 93,762 shares |
The rates and rights derive from Strategy’s filings; its August 31 report set STRC at 12% annually for semi-monthly periods beginning September 16. Closing prices and share volumes reflect September 24 regular-session data from ChartExchange. A single day’s volume does not prove lasting liquidity.
The $100 line is a comparison point, not a uniform legal par or guaranteed redemption price. Strategy’s June 30 filing listed $0.001 legal par for these securities and no $100 stated amount for STRK, though it reported a $100 liquidation preference for STRK at that date. Each series carries its own preferred terms.

Under the August 31 declaration, holders of record on September 15 are due $2.50 per STRF share, $2 per STRK share, and $2.50 per STRD share on September 30, plus $0.50 per STRC share. An additional $0.50 STRC payment falls due October 15 to holders of record on September 30. Both STRC payments represent a 12% annualized rate. The daily proposal has not superseded these declared dates.
STRC’s most recent schedule change demonstrates that a faster calendar can leave the dividend obligation intact. Majorities of common and STRC holders approved its shift from monthly to twice-monthly record and payment dates on June 8. The June 30 filing confirms the change took effect that day without increasing Strategy’s dividend obligation. That precedent does not resolve what approvals or amended terms the proposed daily payments would require across all four series.
The Bitcoin financing test
More frequent cash receipt could make a preferred share more attractive to investors. If sustained buying and firmer trading prices follow, new preferred issuance might become a more appealing capital-raising tool for Strategy’s Bitcoin strategy. This remains a conditional market effect, not a higher annual rate or a stronger legal claim. September 24 prices and volumes cannot reflect a reaction to a September 25 proposal, nor do they indicate proceeds from any future offering.
Strategy’s September 21 cash update underscores why demand for new securities matters even with a large reserve. As of September 20, its USD Reserve, designated for preferred dividends and debt interest, stood at $5.04 billion. A separate $1.05 billion of USD Cash was available for broader treasury uses. During the prior week, $57.4 million of reserve funds covered preferred dividends and interest. Strategy deployed USD Cash to repurchase $174 million of STRC and acquire 950 Bitcoin for $75.7 million, reported no at-the-market share sales, and noted $875.1 million of preferred-share repurchase authority remained.
The buyback supported existing STRC shares in the market; it was not new financing from investors. Daily distributions could improve demand for future preferred sales, but the next meaningful evidence will be specific amended terms and approvals, followed by prices, sustained trading, and actual issuance after any change takes effect. Until then, the proposal alters the payment timetable on paper while the funding benefit remains unproven.
Also Read
- Old Magic Eden NFT approvals put users at risk after whitehat moves 3,832 NFTs
- Crypto Giants Circle and Tether Freeze Stablecoins in Bitget Hacker Wallet
- Crypto ETF Inflows Surpass $3 Billion as Altcoin Products Attract $793 Million
- Geopolitical Risks, Inflation Pressures and Central Bank Policies Shape Market Outlook