




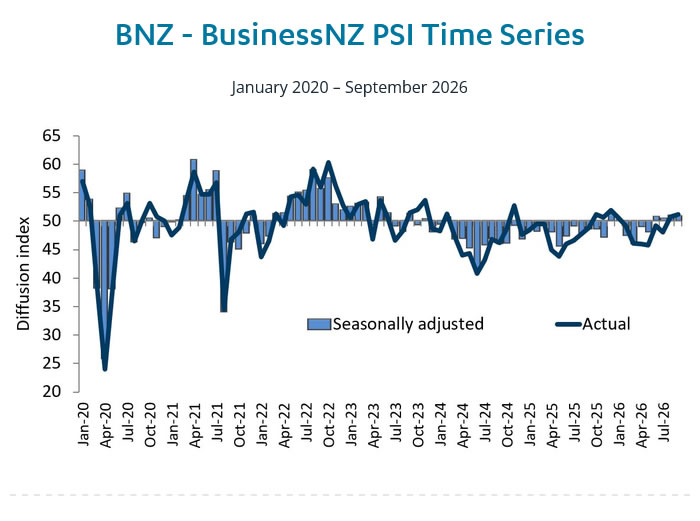
New Zealand’s BNZ–BusinessNZ PMI Services declined slightly from a revised 51.0 in August to 50.9 in September, staying just above the 50-point mark that separates growth from contraction. While the services sector continues to show signs of stabilization, the pace of expansion remains weak. This modest performance stands in contrast to the manufacturing sector, where PMI Manufacturing improved significantly from 53.3 to 56.5 during the same period.
A closer look at the data reveals a mixed trend across key indicators. New Orders/Business reached 52.6, reflecting a stronger pipeline of upcoming work, while Activity/Sales hovered barely above neutral at 50.2. Stocks/Inventories came in at 52.3, but Employment stayed in contraction territory at 49.8, along with Supplier Deliveries at 49.4. According to BNZ, rising fuel costs and tight consumer spending are weighing heavily on the sector—especially retail, which posted the lowest subsector score at 47.4. The gap between new orders and current activity indicates that increased demand has not yet translated into a meaningful uptick in services output.
Although the services sector showed limited momentum, the broader economy received some boost as the combined manufacturing and services composite index rose to 51.6 in September. This supports forecasts for moderate economic growth heading into year-end. Nonetheless, the sharp difference between robust manufacturing results and sluggish services performance highlights the uneven nature of the overall recovery. Analysts note that a more sustainable rebound will depend on strengthening activity levels and a return to job growth, rather than expansion fueled solely by new business intake.
Data Summary
Headline Indicators
Indicator
Aug
Sep
PMI Services
51.0
50.9
PMI Manufacturing
53.3
56.5
PSI Components and Composite
Indicator
Sep
Activity/Sales
50.2
New Orders/Business
52.6
Stocks/Inventories
52.3
Employment
49.8
Supplier Deliveries
49.4
Composite PCI
51.6
Source: BNZ–BusinessNZ September 2026 PSI.
Key Takeaways
- Services expansion remains fragile: PMI Services eased from a revised 51.0 to 50.9, only marginally above the 50-point threshold separating expansion from contraction.
- New orders offer encouragement, but activity lags: New Orders/Business at 52.6 was the strongest subindex reading since June, while Activity/Sales barely expanded at 50.2. Improving demand has yet to translate into stronger services activity.
- Employment continues to constrain the recovery: Employment at 49.8 remained below 50. BNZ also identified elevated fuel prices and constrained household spending as pressures on the sector, with retail particularly weak at 47.4.
- Manufacturing is substantially stronger than services: PMI Manufacturing climbed to 56.5, while the combined composite index reached 51.6. This supports a picture of moderate economic growth, although the divergence between sectors highlights an uneven recovery.
Also Read
- RBA’s Kent Questions Whether Rate Tightening Is Sufficient as Labor Market Cools
- Deutsche Bank Plans 2027 Asian Crypto Custody Expansion Amid Imminent German Launch
- Major U.S. Issuers Challenge SEC Tokenized‑Stock Framework Ahead of OKXICE Launch
- Zcash NU7 Upgrade Leaves Sprout Funds Unspendable Without Migration Path