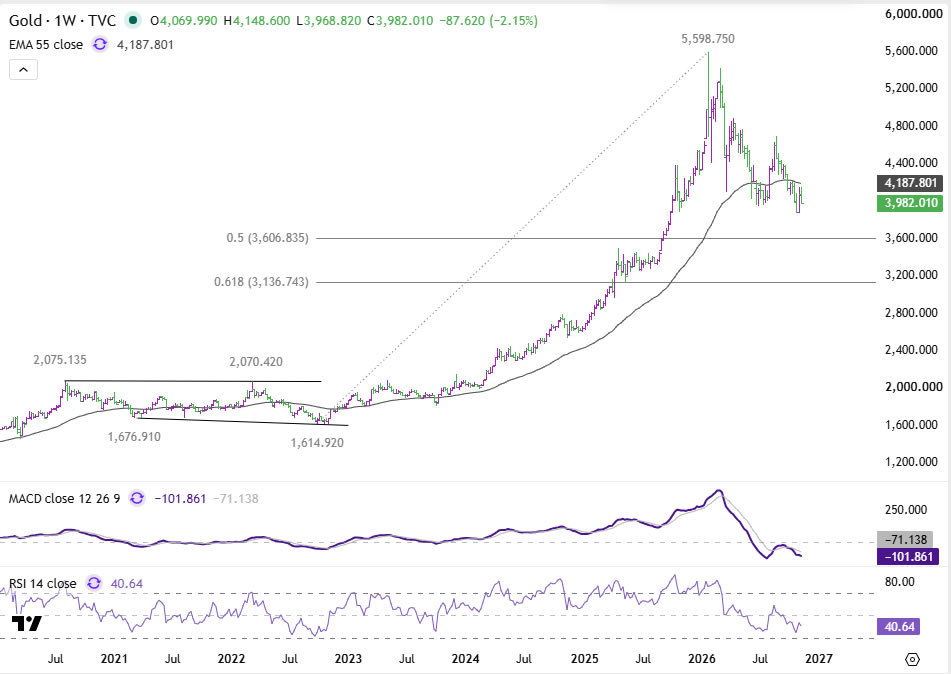
TL;DR: Gold’s failed rebound has shifted the near-term bias back toward a retest of the early-November low near 3,870, though a decisive breakdown may have to wait. Hawkish Fed repricing has already absorbed much of the expected tightening, leaving limited room for another major shift in rate expectations before the December 4 payrolls unless a fresh catalyst arrives.
Why Might Gold Retest Support Without Breaking It?
Gold’s failed rebound has revived a bearish technical outlook, with a retest of the early-November low at 3,869.96 now favored after the metal reversed from resistance near 4,150 and slipped back below 4,000. Hawkish Fed repricing and dollar strength have weighed on the decline, but the scope for another substantial shift in U.S. rate expectations may be limited before the December 4 nonfarm payrolls report. With markets already pricing considerable tightening, gold could retest 3,870 without breaking decisively below it, unless fresh policy surprises or other market catalysts trigger additional selling.
Gold’s Failed Rebound Leaves It Vulnerable to Another Test of 3,870
Gold’s recovery from 3,869.96 reached 4,148.60 earlier this week, almost precisely matching the falling daily 55 EMA near 4,147. The rebound also stopped short of the 38.2% retracement of the decline from 4,697.07 to 3,869.96 at 4,185.92, reinforcing the view that the recovery was corrective rather than the beginning of a sustained bullish reversal.
The subsequent selloff brought gold back below 4,000, with a firm break beneath the four-hour 55 EMA near 4,042 supporting the case that the recovery from 3,869.96 has completed.

The immediate technical outlook therefore favors another decline toward 3,869.96. However, a retest does not necessarily imply that support will break.
Strong buying interest around the previous low could produce another rebound, extending the corrective pattern rather than confirming a deeper bearish move. A recovery through minor resistance at 4,066.93 would suggest that another rising leg may already be developing, potentially reopening 4,148.60.
The broader bearish bias nevertheless remains intact while gold trades below the falling daily 55 EMA and the nearby 4,185.92 Fibonacci resistance.
Fed Tightening Expectations Are Already Substantially Priced
The recent decline has coincided with a sharp strengthening in the dollar and U.S. Treasury yields following October’s inflation surprise and hawkish remarks from several Fed officials.
The more important question for gold now is how much additional tightening markets can price without significant new information.
CME FedWatch shows a December rate hike fully priced, with a 90.8% probability of a 25 basis point move and 9.2% for a larger 50 basis point move.
January pricing is also notably hawkish. The probability of the federal funds target range reaching at least 4.25–4.50% stands at approximately 67.6%, compared with just 20.9% a week earlier.
This indicates that markets have shifted substantially toward expectations of at least 50 basis points of cumulative tightening by January, through either consecutive 25 basis point increases or a larger December adjustment.
- December: 90.8% probability of a 25 basis point hike, 9.2% for 50 basis points
- January: about 67.6% probability of the target range reaching at least 4.25–4.50% (20.9% a week earlier)
The repricing helped lift the U.S. two-year Treasury yield to around 4.75%, while the dollar approached the 103 level. Together, higher interest rates and dollar strength have created a difficult environment for gold.
However, the easier phase of hawkish repricing may already be behind the market. A December hike is fully priced, while January expectations already favor additional tightening.
Further hawkish repricing is certainly possible, particularly if the probability of a 50 basis point December move increases or expectations extend toward further hikes beyond January. But another substantial adjustment would likely require stronger evidence that the Fed intends to move more aggressively than markets currently anticipate.
This may limit the ability of the existing Fed tightening narrative alone to generate another major wave of gold selling.
Hawkish Bound on Fed Repricing Could Delay Gold’s Breakdown
The distinction between a retest of 3,869.96 and a decisive breakdown is important. Gold’s deteriorating technical structure favors another test of support, but the hawkish bound on Fed repricing could limit the selling pressure needed to break it.
Markets have already moved substantially toward expectations of consecutive rate increases. With January pricing implying approximately 43 basis points of cumulative tightening, there is only around 7 basis points of additional tightening to price before two full 25 basis point hikes are reflected in expectations. A December hike is already fully priced, while the probability of at least 50 basis points of cumulative tightening by January has risen sharply over the past week.
This creates a near-term hawkish bound, rather than a hard ceiling, on further Fed repricing. Another substantial shift would require markets to price a greater probability of a 50 basis point December hike or extend tightening expectations further into 2027. Simply repeating the hawkish message already delivered by Fed officials may not be sufficient.
The comments of New York Fed President John Williams could be particularly important. Williams previously indicated that he saw little reason to expect more than one additional hike in 2026 and no immediate need for further increases in 2027, although those remarks preceded October’s stronger-than-expected CPI. His latest assessment could clarify whether the inflation surprise has changed his outlook.
A more hawkish position could reinforce expectations for back-to-back December and January hikes. However, if Williams supports a December increase without signaling urgency for further tightening, the scope for additional hawkish repricing may be limited. A more cautious assessment could even prompt markets to scale back January expectations, easing pressure on gold.
Friday’s U.S. producer inflation report presents another test, although October’s CPI has already established a relatively firm inflation backdrop. A substantial PPI surprise could alter expectations, but a reading broadly consistent with forecasts may do little to extend the existing tightening narrative.
The next major opportunity for a broader reassessment is the November nonfarm payrolls report on December 4. Until then, the combination of substantial tightening already priced and limited fresh economic evidence could constrain further dollar and Treasury yield gains driven specifically by Fed expectations.
There are important qualifications. The hawkish bound is not a limit on gold’s downside. A further energy shock, a stronger shift toward a 50 basis point December hike, or developments unrelated to monetary policy could still trigger additional selling. Gold is also sensitive to longer-term yields, dollar movements and investor positioning, not just expectations for the next two Fed meetings.
Nevertheless, the existing Fed repricing may be sufficient to carry gold back toward 3,869.96 without providing the additional momentum needed for a decisive break. If support holds, another corrective rebound could develop while markets await stronger evidence on the Fed’s next moves.
The immediate bearish technical outlook therefore remains intact, but a sustained breakdown below 3,870 may have to wait for a fresh catalyst.
Broader Gold Outlook: 3,600 Becomes Relevant Only After Support Breaks
Gold continues to trade below the falling daily 55 EMA near 4,147, while the 38.2% retracement of 4,697.07 to 3,869.96 at 4,185.92 and the weekly 55 EMA near 4,188 form a broader resistance region.
The failure to overcome these levels keeps the medium-term outlook bearish.
However, the larger downside scenario remains conditional on a firm break below 3,869.96.
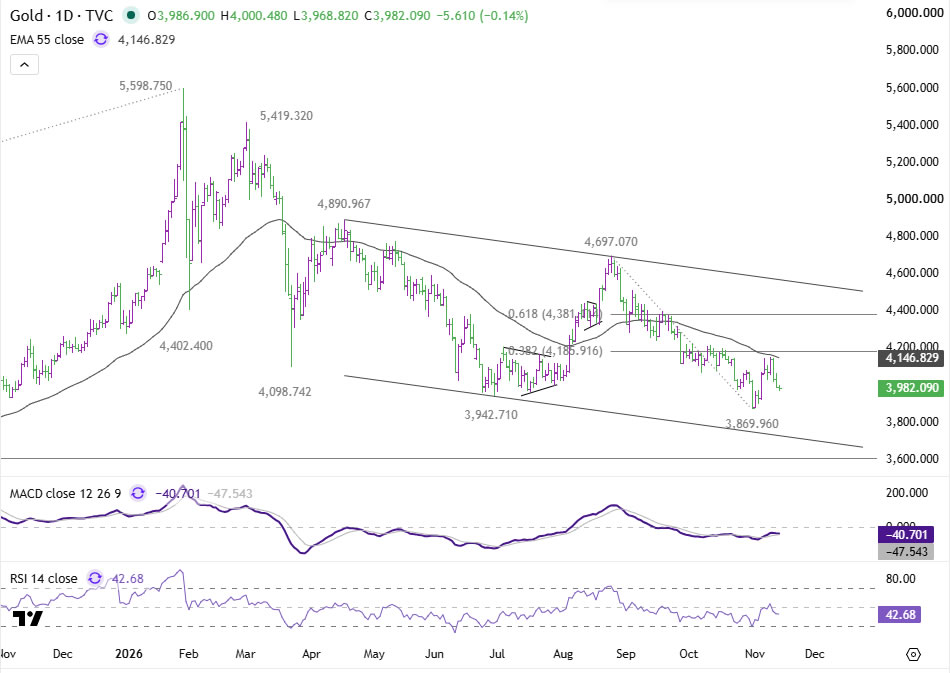
Such a break would suggest that the correction from the 5,598.75 record high is extending, bringing the 50% retracement of the entire advance from 1,614.92 to 5,598.75 at 3,606.83 into focus.
The next major downside reference would therefore be the psychological 3,600 region, rather than an immediate target while 3,870 remains intact.
Conversely, another successful defense of 3,869.96 could produce a rebound toward 4,066.93 and potentially 4,148.60. A sustained recovery above the 4,185.92–4,187.80 resistance area would weaken the broader bearish interpretation.
For now, gold’s technical structure favors another test of 3,870, but the case for a decisive breakdown is less compelling from the Fed repricing perspective alone.
With December and January tightening expectations already substantially reflected in market prices, the next major bearish extension may depend on fresh policy evidence or developments outside the Fed outlook.
The retest could come first. The breakdown may have to wait.
Key Takeaways
- Gold reversed from 4,148.60, just below the 4,185.92 Fibonacci resistance, and slipped below 4,000, favoring a retest of the 3,869.96 low.
- A December hike is fully priced (90.8% for 25 basis points), and January pricing implies about 43 basis points of cumulative tightening, leaving only about 7 basis points to price before two full hikes.
- A retest does not mean a break: a recovery through 4,066.93 would suggest another rising leg could develop, potentially reopening 4,148.60.
- The hawkish bound is not a limit on downside, since an energy shock, a stronger shift toward a 50 basis point December hike or non-Fed developments could still trigger selling.
- A firm break below 3,869.96 would bring the 3,606.83 retracement and the 3,600 region into focus; Williams’ comments, Friday’s PPI and the December 4 payrolls are the next tests.