



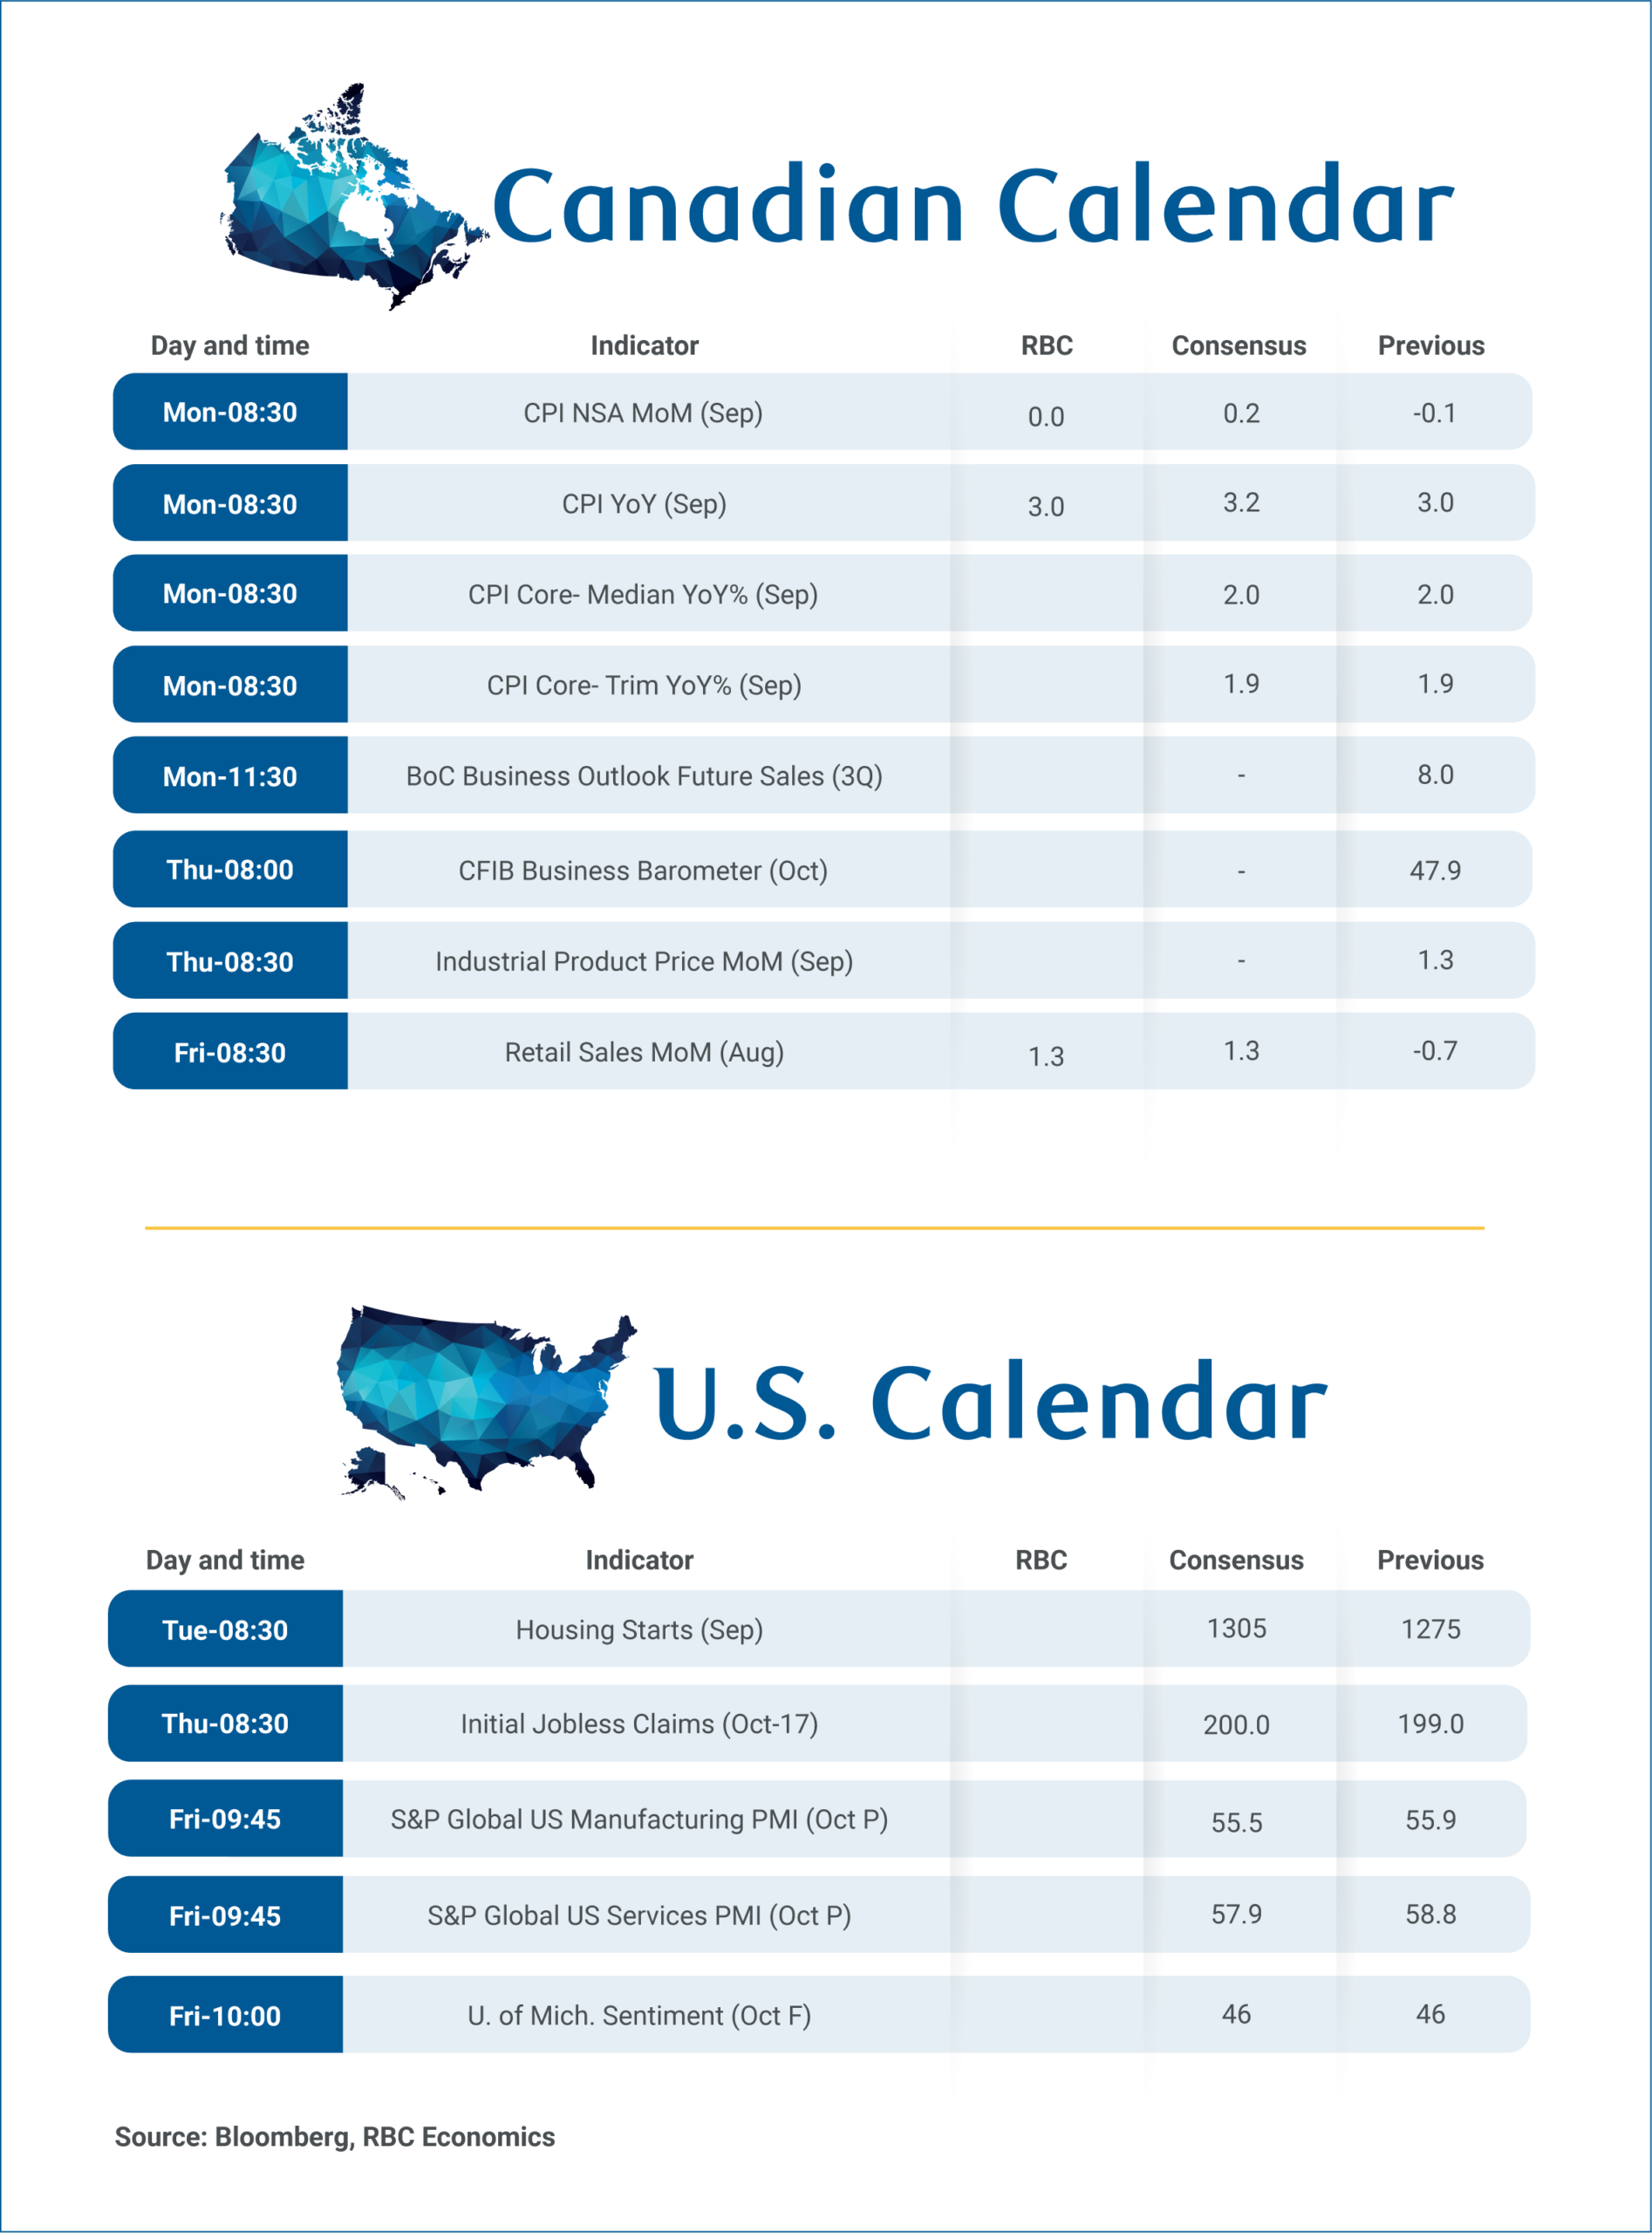
Canadian inflation figures and the Bank of Canada’s third-quarter Business Outlook Survey, released on Monday, will be closely scrutinized for indications of whether inflation pressures from sustained high energy costs are spreading across the broader economy.
These reports will serve as critical inputs for the Bank of Canada’s upcoming interest rate decision on October 28. Policymakers remain cautious that elevated oil prices could spill over into non-energy sectors or influence rising inflation expectations among businesses and consumers.
However, inflation risks must be weighed against a gradually improving, yet still soft, economic landscape. Progress has been uneven, with GDP growth projected to slow in the second half of 2026 following a robust second quarter. Employment declined consecutively in August and September, and the unemployment rate has stabilized around 6.5% over the past three months after a decline in the previous year.
For the time being, we anticipate a delicate balance between inflation and growth risks, which is likely to keep the Bank of Canada in a cautious holding pattern for the remainder of 2026.
Inflation held up by persistently elevated energy prices
We forecast Canada’s headline Consumer Price Index to remain steady at 3.0% year-over-year in September, marking a third consecutive month at this level. Energy inflation is likely to have accelerated as gasoline and furnace oil prices rose significantly compared to August. However, food inflation is expected to continue its gradual moderation.
Excluding food and energy, core inflation is projected to ease slightly to 1.8% in September, down from 2.1% in August. We continue to anticipate limited pass-through of energy inflation into core components, with the exception of airfares, but will monitor transportation categories closely as they are most vulnerable.
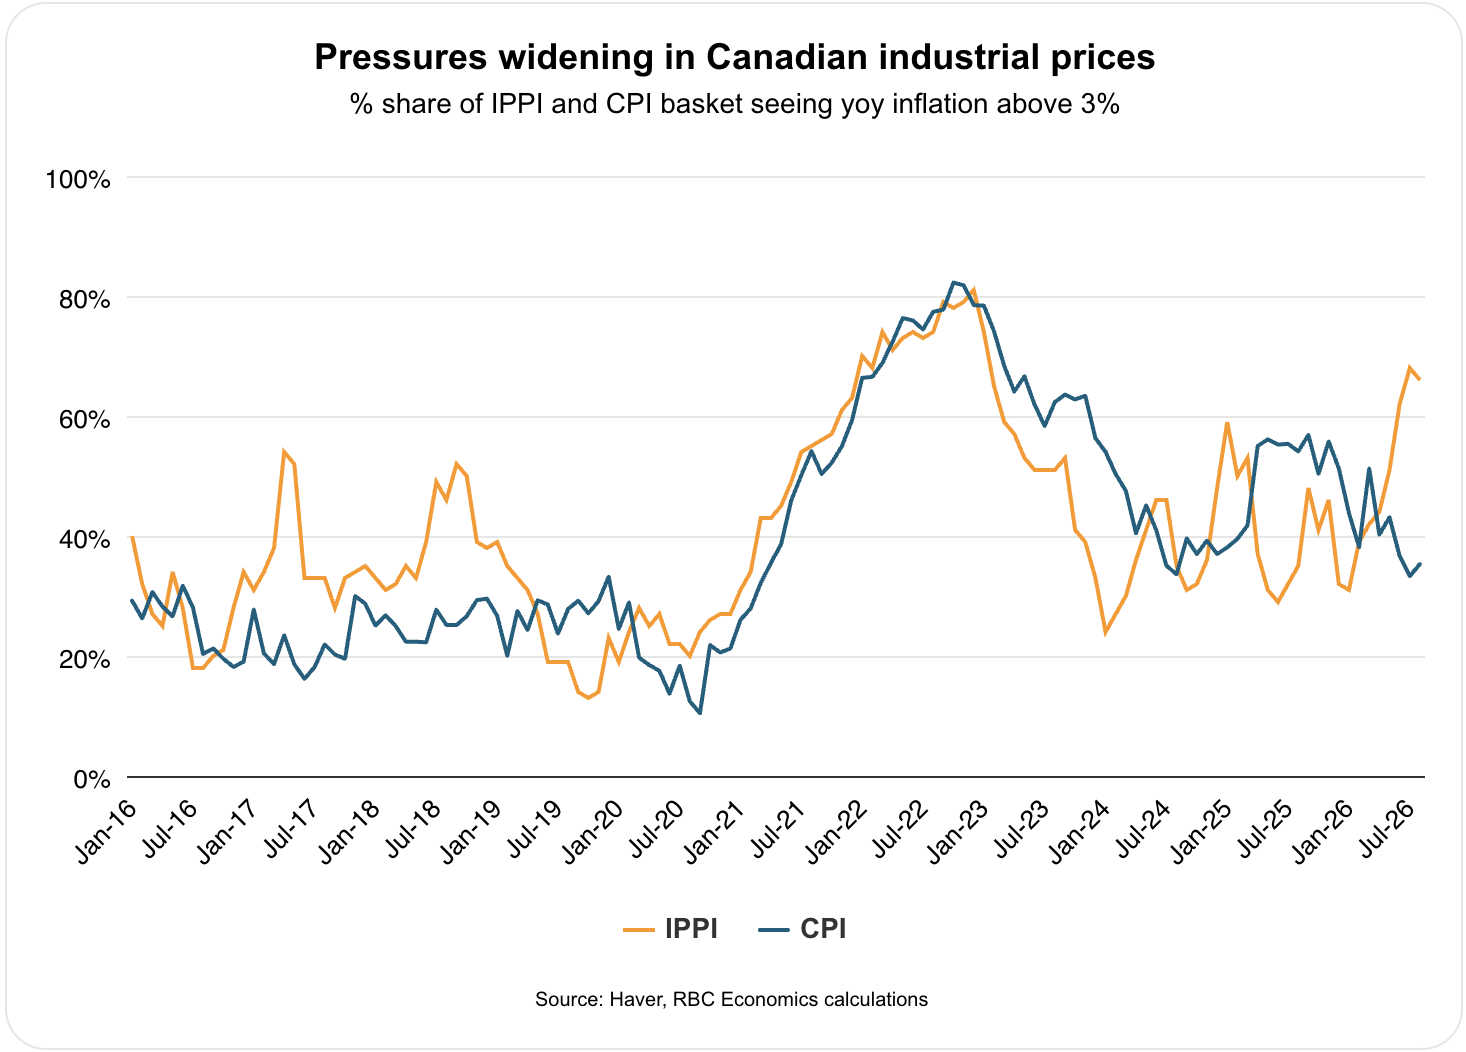
Our Consumer Price Index diffusion index, which measures the breadth of inflationary pressures, has not yet indicated a problematic widening of price increases. The share of the consumer basket experiencing annual price growth above 3% remained narrow at 35% in August, significantly down from 54% a year ago.
Nevertheless, the diffusion index for industrial production prices has already shown a concerning spread. However, it will take considerable time for these price increases to filter down through production layers and ultimately reach consumers on store shelves, requiring energy prices to remain elevated in the interim.
Business survey to unveil shifting inflation expectations
Complementing the consumer price data, the third-quarter Business Outlook Survey will provide qualitative insights into the impact of elevated energy inflation, including how it has shaped corporate expectations.
Business sentiment softened in the second quarter due to higher fuel costs and lingering trade uncertainties. In the third quarter, these risks escalated rather than subsided, as the survey period (early to mid-August) coincided with rising oil prices and renewed trade tensions following the imposition of new U.S. Section 338 measures on August 22. We expect these uncertainties to have further dampened business outlooks.
Analysts will closely monitor changes in firms’ future sales outlooks, investment and hiring intentions, reported input and selling price increases, as well as shifts in inflation expectations. We anticipate another uptick in short-term inflation expectations, while medium- to longer-term expectations remain relatively well anchored near the 2% target.
On Monday, October 19, Albertans will vote on whether to initiate a process toward a future binding referendum on provincial separation. Advance polling opened on Tuesday.
Next Friday’s retail sales report is expected to align with Statistics Canada’s advance estimate of a 1.3% increase in August. With gas prices remaining flat month-over-month, this expansion was likely driven by rising sales volumes. This aligns with RBC card transaction data, which showed robust spending trends over the summer and continued growth in September, albeit at a more moderate pace.