



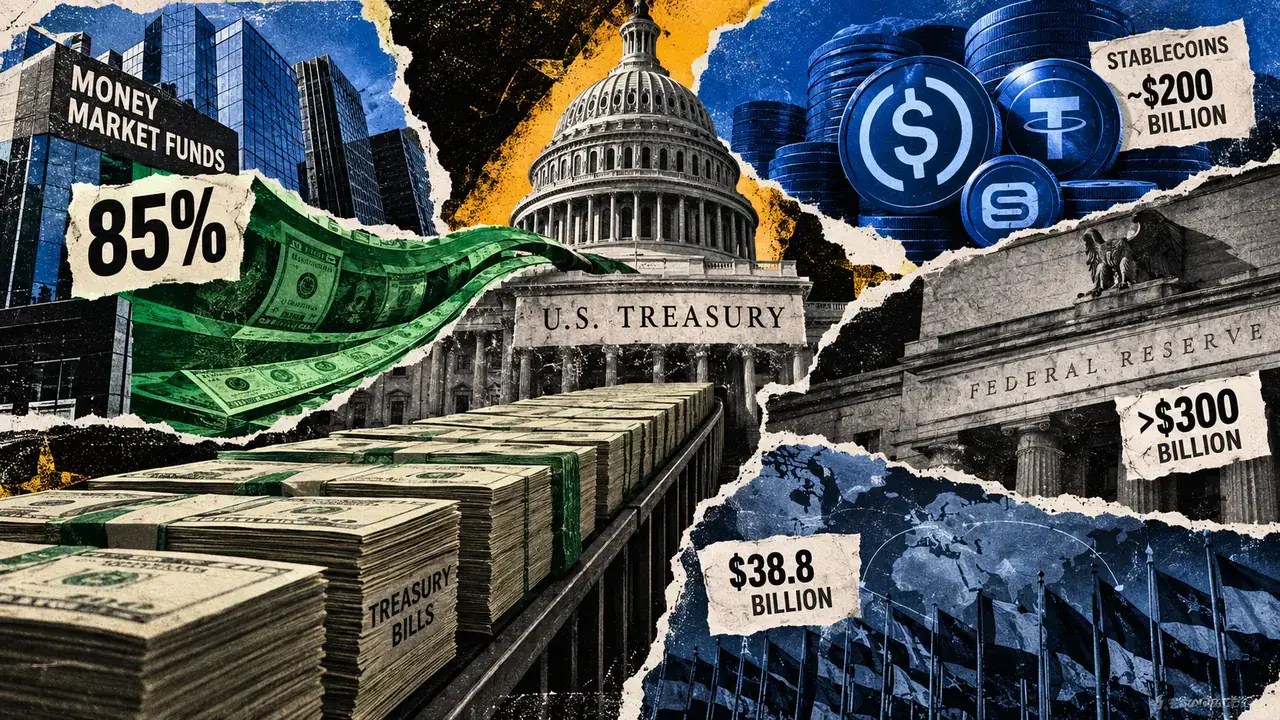
Money-market mutual funds absorbed roughly 85% of the U.S. government’s latest Treasury-bill issuance surge, making them the clearest source of incremental demand behind the summer wave.
Treasury reported that net bill supply rose by more than $550 billion in July and August, an increase of about 8% over two months. According to Deputy Treasury Secretary Francis Brooke’s Sept. 22 remarks, money funds took up most of that added supply.
Stablecoin issuers are also major holders of short-term government debt, with Treasury valuing their holdings at nearly $200 billion. However, that figure represents a stock of Treasury bills and other near-maturity securities, whereas the money-fund estimate refers to purchases linked to a particular two-month increase in supply. The categories may overlap because stablecoin reserves can be invested through government money-market funds and repurchase agreements.
Together, the figures show that stablecoins have become a meaningful Treasury-linked investor base and could expand their role as regulation develops. Yet the documented increase in demand during 2026 came mainly from money funds and the Federal Reserve, while foreign investors added to their holdings in July.
What Treasury’s buyer breakdown reveals
Four key figures provide context, but they use different measurement periods and track different concepts. They should not be combined into a single buyer total.
| Buyer or holder | Reported amount | Measurement window | What the figure establishes |
|---|---|---|---|
| Money-market mutual funds | About 85% of more than $550 billion | July-August 2026 | Share of additional bill supply absorbed |
| Stablecoin providers | Nearly $200 billion | Holdings stock; date not specified | Bills and other near-maturity Treasuries owned |
| Federal Reserve | More than $300 billion | 2026 through Sept. 22 | Bill purchases through two portfolio channels |
| Foreign residents | $38.8 billion increase | July 2026 | One-month change in foreign bill holdings |

Treasury’s 85% estimate concerns only the additional bills issued in July and August, not the entire bill market. Brooke did not break down the remaining share by buyer in his remarks.
The stablecoin figure serves a separate purpose: it indicates that issuers have become a substantial source of demand for short-dated government assets. Treasury grouped the nearly $200 billion across Treasury bills and other near-maturity securities, without identifying the composition of the holdings or how much was purchased during the summer.
Issuer disclosures illustrate why stablecoin and money-fund demand can overlap. Circle said in its second-quarter filing that approximately 84% of USDC reserves were held in the Circle Reserve Fund as of June 30. The company identifies the vehicle as a Rule 2a-7 government money-market fund.
As a result, USDC-related reserve demand may be reflected in money-fund holdings. Circle represents only one issuer, so that allocation cannot be generalized to the entire stablecoin market. It does, however, demonstrate how the broader buyer categories can overlap.
The fund’s assets also show that its Treasury exposure extends beyond direct bill ownership. Its annual shareholder report listed $19.111 billion in direct Treasury obligations and $46.998 billion in repurchase agreements as of April 30. Although the repos were collateralized by Treasuries, they were recorded separately from direct obligations. Because that portfolio date predates Circle’s June reserve disclosure and holdings can change, the filings establish the structure of the exposure rather than an exact June allocation.
Treasury presented stablecoin demand as a potential source of future growth. Brooke said issuers may continue expanding and increase their Treasury holdings as rules implementing the GENIUS Act are finalized. That qualified language points to a possible regulatory-driven source of demand, not a forecast or an explanation for the July-August supply absorption.
The Fed and foreign investors add demand on different timelines
The Federal Reserve has also become a significant bill buyer in 2026. Treasury said it purchased more than $300 billion through reserve-management operations and reinvestment of principal payments from agency securities.
The Fed’s July monetary policy report had recorded nearly $250 billion in bill purchases through July 1. About $160 billion came from reserve-management purchases, while roughly $90 billion came from reinvestments of principal payments on agency mortgage-backed securities. Treasury’s later figure reflects a more recent cutoff.
These purchases take place in the secondary market rather than through direct Treasury auctions. The operations are intended to maintain ample reserves and shape the composition of the System Open Market Account, distinguishing them from direct government financing and conventional quantitative easing.
The Fed’s published balance sheet supports the scale of that expansion. Bill holdings stood at $233.592 billion on Dec. 31, 2025, in the Jan. 2 H.4.1 release, and reached $550.482 billion on Sept. 16, in the Sept. 17 release. The difference reflects a net change in the stock of holdings, not gross purchases, and cannot be assigned specifically to July-August issuance. It does show how rapidly bills became a larger component of the Fed’s portfolio.
Foreign demand improved before Treasury published its buyer breakdown. Foreign residents increased their bill holdings by $38.8 billion in July, according to the Treasury International Capital release. That followed declines of $20.0 billion in April, $43.5 billion in May and $29.0 billion in June.
Private foreign holdings rose by $45.0 billion in July, while foreign official holdings declined by $6.3 billion. The rebound indicates a return by overseas buyers after three consecutive monthly decreases, but it covers only one month and measures foreign holdings rather than every buyer category. Treasury also warns that custody-based TIC data can obscure the beneficial owner when securities are held through third countries or managed by foreign portfolio managers.
Overall, the data point to broad demand for short-term U.S. debt, though the buyer figures are not directly interchangeable. Money funds accounted for most of Treasury’s measured July-August supply increase, the Fed generated substantial year-to-date secondary-market demand and foreign holdings rebounded in July. Stablecoin issuers remain major holders within this market, with reserve structures that can route demand through money funds and repurchase agreements.
The regulatory outlook could increase stablecoins’ role in future Treasury financing. The latest issuance surge occurred before that potential could be measured as a distinct flow, leaving traditional money funds as the buyer category Treasury identified most clearly.
Also Read
- XRP Poised for Strongest September Performance Since 2022
- Bitcoin ETFs just erased a $5.7 billion hole, but profit-taking is swallowing the new demand
- Fed Governor Barr Warns Policymakers Are Out of Sync, Signals More Rate Hikes Ahead
- Bitcoin’s $16 Billion Quarterly Options Expiry Looms with Heavy Call Concentration