







UK private-sector activity gathered momentum in October, with the headline PMI Composite climbing from 52.0 to 53.1—its highest level in eight months and a fourth straight month of expansion. The services index rose from 52.1 to 53.1, while manufacturing advanced from 51.9 to 52.8, both surpassing consensus forecasts. Factory output accelerated from 51.5 to 53.1, registering its strongest growth in 25 months. The broad-based pickup reflected a resurgence in client demand, with new orders expanding at the fastest rate since September 2024 across both domestic and export channels.
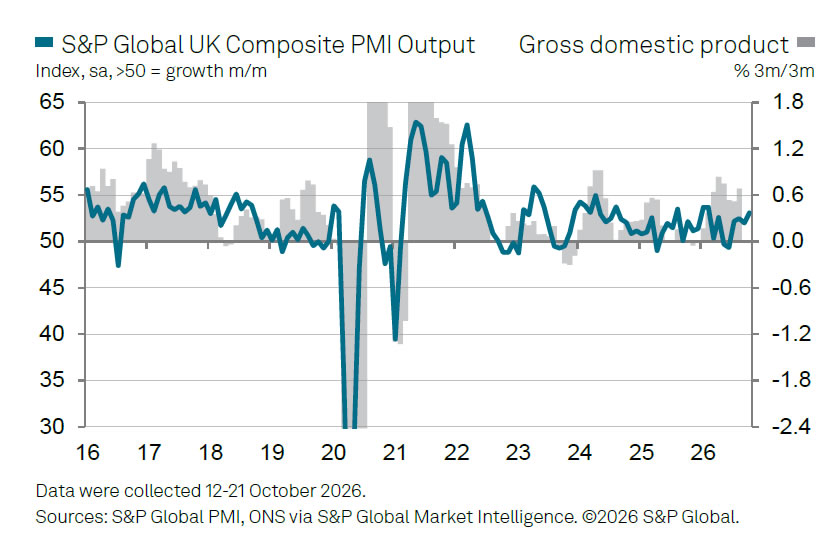

Employment returned to growth for the first time since September 2022, ending a two-year stretch of job cuts in the private sector. The turnaround was led by renewed hiring among service providers, while manufacturers continued to trim payrolls modestly. Firms pointed to fuller order books, new project pipelines, and longer-term expansion plans as drivers of recruitment, though the overall increase in headcount remained marginal. Some respondents also noted firmer demand linked to artificial-intelligence investment and technology services. Nevertheless, hiring intentions stayed cautious: backlogs kept falling, and weak consumer sentiment, geopolitical uncertainty, and subdued construction activity continued to weigh on capacity pressures.
On the cost side, input-price inflation quickened to its fastest pace since June, propelled by higher energy, raw-material, and transportation costs in manufacturing. Supplier delivery times deteriorated at the sharpest rate since May as shipping disruptions and shortages of semiconductors and electronic components persisted. Despite the upstream pressure, selling-price inflation eased slightly, suggesting firms absorbed much of the cost increase rather than passing it through to customers. Business confidence improved modestly but remained below its long-run average. The October survey thus signals strengthening growth momentum and an encouraging, albeit tentative, hiring recovery, while persistent cost pressures and supply-chain frictions cloud the outlook.
Data Summary
Headline PMI Data
| Indicator | Previous | Expected | Current |
|---|---|---|---|
| PMI Composite | 52.0 | — | 53.1 |
| PMI Manufacturing | 51.9 | 51.8 | 52.8 |
| PMI Services | 52.1 | 51.8 | 53.1 |
| Manufacturing Output | 51.5 | — | 53.1 |
Readings above 50 indicate expansion, while readings below 50 indicate contraction. Survey responses were collected October 12–21.
Additional Survey Details
| Indicator | October Development |
|---|---|
| Private-Sector Output | Fourth consecutive expansion; fastest growth in eight months |
| Manufacturing Output | Strongest expansion in 25 months |
| New Orders | Fastest growth in 25 months |
| Domestic and Export Demand | Both improved |
| Overall Employment | First increase since September 2022 |
| Services Employment | Returned to growth |
| Manufacturing Employment | Slight decline |
| Backlogs of Work | Continued declining, extending a trend of approximately three and a half years |
| Input Cost Inflation | Fastest since June |
| Supplier Delivery Times | Greatest deterioration since May |
| Manufacturing Stocks of Purchases | Fifth consecutive monthly decline |
| Manufacturing Finished-Goods Inventories | Largest decline since June 2025 |
| Selling Price Inflation | Eased slightly |
| Business Confidence | Improved modestly, but remained below long-run average |
Key Takeaways
- UK private-sector growth accelerates to an eight-month high: The composite PMI rose from 52.0 to 53.1, marking a fourth straight month of expansion. Both manufacturing and services strengthened, signalling broader momentum at the start of Q4.
- Manufacturing and services both beat expectations: The manufacturing PMI climbed from 51.9 to 52.8, while services improved from 52.1 to 53.1. Factory output surged from 51.5 to 53.1, its fastest expansion in 25 months.
- New orders point to firmer underlying demand: Total new business grew at the quickest pace since September 2024, underpinned by improving domestic and export orders. Some firms cited stronger demand tied to AI investment and technology services.
- Employment turns positive after two years: Private-sector staffing increased for the first time since September 2022, driven by renewed services hiring. Manufacturing employment continued to edge lower, leaving the overall gain marginal and the recovery tentative.
- Hiring stays cautious despite better demand: Companies reported limited pressure on operating capacity as backlogs fell further. Weak consumer confidence, geopolitical uncertainty, and soft construction demand remain headwinds.
- Manufacturing cost pressures intensify: Input-cost inflation accelerated to its fastest since June, led by higher energy, raw-material, and transport expenses. Shipping disruptions and electronic-component shortages lengthened supplier delivery times the most since May.
- Selling-price inflation moderates despite rising costs: Prices charged to customers rose at a slightly slower pace than in September, indicating accelerating upstream costs were not fully passed through.
- Momentum improves but risks persist: Stronger output, new orders, and initial hiring gains suggest an encouraging start to Q4. However, elevated costs, supply-chain constraints, and below-average confidence leave the durability of the upturn uncertain.
Also Read
- Ripple CTO David Schwartz Jokes About Matt Damon’s Swell 2026 Appearance Amid Water.org Partnership
- Brent Nears $120 as Nasdaq Tests 25,800 and US 10-Year Yield Hovers at 5%
- GBP/USD Weekly Forecast: Navigating Key Support and Resistance Levels
- Ethereum staking yield is losing to cash rates, so why are investors still lining up?


