




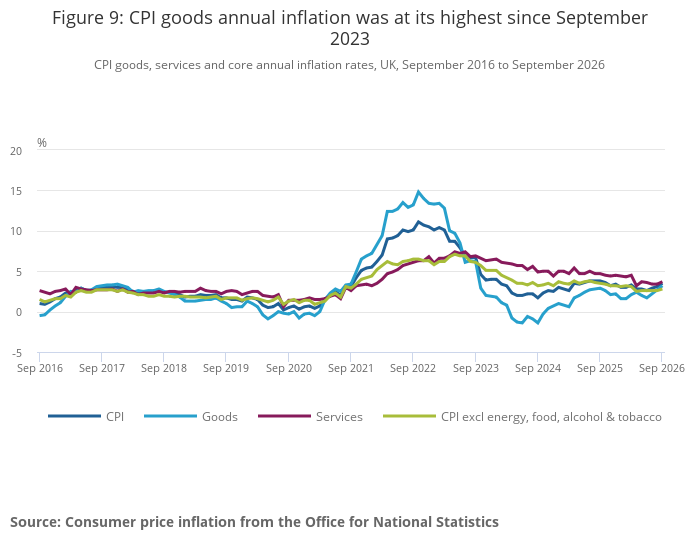
UK inflation picked up more than anticipated in September, with the headline consumer price index rising from 3.1% to 3.5% year over year. The print surpassed market expectations of 3.4% and marked the fastest pace since October 2025. On a monthly basis, CPI increased 0.4%, compared with 0.5% in August and the forecast of 0.3%. Core inflation also firmed, moving from 2.6% to 2.8% year over year against projections of 2.7%, while services inflation accelerated from 3.4% to 3.7%. The synchronized gains across headline, core, and services measures point to a more complex inflation outlook than the headline surprise alone would indicate.
Motor fuel costs were the primary driver behind the acceleration in headline inflation. Annual transport inflation jumped from 4.6% to 6.6%, largely because motor fuel inflation rose from 23.0% to 29.8%. Petrol prices climbed by 8.2 pence per litre during September, compared with a modest decline in the same month last year, while diesel prices increased by 10.7 pence. Average petrol and diesel prices reached their highest levels since August and July 2022, respectively, underscoring how elevated energy costs continue to feed into consumer prices.
Underlying price pressures also intensified, though the breadth of the increase was uneven. Goods inflation accelerated from 2.7% to 3.2%, while the rise in services inflation partly reflected airfares declining less steeply than in the prior year. Housing and household services inflation increased from 4.9% to 5.3%, and recreation and culture inflation climbed from 1.6% to 2.3%. In contrast, restaurants and hotels inflation eased from 4.1% to 3.8%, offering the largest partial offset to the headline acceleration, while food inflation held steady at 1.3%. These divergent movements suggest that inflation pressures have widened in certain areas without spreading uniformly across the economy.
The September report renews concerns about inflation persistence, especially given the uptick in core and services prices. At the same time, airfare base effects and softer restaurant and hotel inflation make it more difficult to gauge underlying domestic momentum. For the Bank of England, the firmer readings support maintaining a restrictive policy stance, though they do not by themselves determine how much further tightening might be required. Although a November rate increase is already widely priced into markets, the more significant question is whether persistent underlying inflation justifies additional rate rises beyond the next meeting.
Data Summary
UK Consumer Price Inflation — September 2026
| Indicator | Previous | Forecast | Current |
|---|---|---|---|
| CPI Y/Y | 3.1% | 3.4% | 3.5% |
| CPI M/M | 0.5% | 0.3% | 0.4% |
| Core CPI Y/Y | 2.6% | 2.7% | 2.8% |
| CPI Services Y/Y | 3.4% | — | 3.7% |
| CPI Goods Y/Y | 2.7% | — | 3.2% |
Selected CPI Components — Annual Inflation
| Component | Previous | Current |
|---|---|---|
| Motor fuels | 23.0% | 29.8% |
| Transport | 4.6% | 6.6% |
| Housing and household services | 4.9% | 5.3% |
| Recreation and culture | 1.6% | 2.3% |
| Communication | 5.3% | 5.8% |
| Restaurants and hotels | 4.1% | 3.8% |
| Food and non-alcoholic beverages | 1.3% | 1.3% |
Source: UK Office for National Statistics, October 21, 2026.
Key Takeaways
- Headline inflation exceeds forecasts: UK CPI accelerated from 3.1% to 3.5% year over year in September, beating expectations of 3.4% and reaching its highest rate since October 2025. Monthly inflation eased from 0.5% to 0.4% but remained above the expected 0.3%.
- Core and services inflation also quicken: Core CPI rose from 2.6% to 2.8%, above forecasts of 2.7%, while services inflation increased from 3.4% to 3.7%. The concurrent increases point to a more demanding underlying inflation picture, though they do not confirm uniform strengthening in domestic price pressures.
- Motor fuels drive the headline gain: Transport inflation jumped from 4.6% to 6.6%, propelled primarily by motor fuel inflation accelerating from 23.0% to 29.8%. Higher petrol and diesel prices supplied the largest upward contribution to the annual change in CPI inflation.
- Goods inflation and other categories firm: Goods inflation increased from 2.7% to 3.2%, its highest rate since September 2023. Housing and household services inflation rose to 5.3%, while recreation and culture inflation accelerated to 2.3%, signaling additional sources of upward price pressure.
- Services inflation includes notable caveats: Part of the acceleration reflected airfares falling less sharply than a year earlier. Meanwhile, restaurants and hotels inflation eased from 4.1% to 3.8%, providing the largest downward offset to the headline increase. The services data therefore present a mixed picture of underlying momentum.
- Food inflation remains contained: Food and non-alcoholic beverages inflation was unchanged at 1.3%, with prices declining 0.2% during September. This contrasts with the acceleration in transport and selected other categories, reinforcing the uneven composition of the inflation increase.
- Bank of England faces renewed inflation concerns: Firmer headline, core, and services readings reinforce the case for maintaining a restrictive monetary policy stance. However, with a November rate hike already heavily anticipated in earlier market pricing, the more consequential issue is whether underlying inflation remains persistent enough to justify additional tightening beyond November.
Also Read
- ECB’s Lane Highlights Expanded Euro Liquidity Backstop Supporting Sovereign Bond Markets
- Ripple Unveils 24/7 Stock Derivatives, But HSBC Warns of Shallow Markets
- Australian Dollar Gains on Revived RBA Rate Hike Bets Ahead of Key Inflation Data
- Swiss Regulator Grants First Bitcoin ETF Direct Investment Access Under Retail Framework