







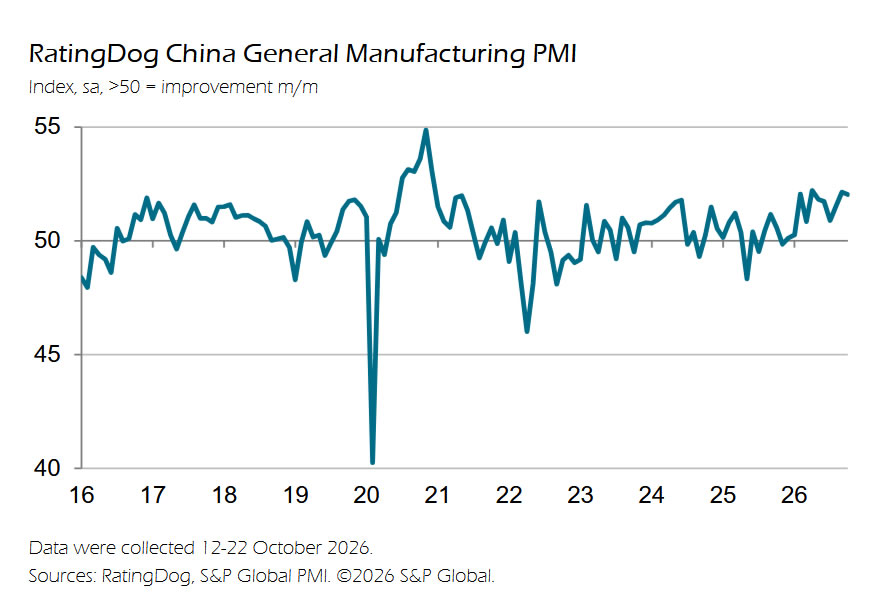
China’s private manufacturing sector continued to expand in October. The RatingDog PMI Manufacturing slipped to 52.0 from 52.1, marking the 11th straight month above the 50‑point expansion threshold—the longest stretch since mid‑2021. Output grew at its quickest rate since April, buoyed by robust new orders. New business increased for the 17th consecutive month, while export orders rose for the fourth month, though at a slower pace. Rising demand and output prompted firms to boost purchases at the fastest rate in eight months and to add modestly to payrolls.
Nevertheless, the stronger activity did not lift selling prices. Heightened competition caused manufacturers to cut factory‑gate prices for the second time in three months, and export prices fell for the first time in almost a year. Input costs, however, kept climbing, though the rate of inflation moderated from September as supply conditions improved. Delivery times shortened for the first time since February, and firms continued to build up purchase stocks. Hiring edged higher, but backlogs rose for the ninth month in a row, indicating that capacity is still struggling to keep up with demand.
The survey underscores a split between rising manufacturing activity and lingering price weakness. Solid orders and accelerating output signal ongoing expansion, but falling selling prices together with rising input costs highlight pressure on profit margins. Business confidence fell to a nine‑month low as concerns about higher costs and competition grew. Together, these trends show that stronger output is driving growth while the sector’s operating environment remains challenging.

Data Summary
China RatingDog PMI Manufacturing — October 2026
| Indicator | Sep | Oct |
|---|---|---|
| PMI Manufacturing | 52.1 | 52.0 |
Components
| Component | October Trend |
|---|---|
| Output | Fastest growth since Apr |
| New Orders | Solid growth, broadly unchanged |
| Export Orders | Three-month low, still expanding |
| Employment | Marginal increase |
| Backlogs | Ninth consecutive monthly increase |
| Purchasing Activity | Fastest growth in eight months |
| Stocks of Purchases | Strongest increase in five months |
| Supplier Delivery Times | First shortening since Feb |
| Input Prices | Inflation eased |
| Output Prices | Renewed marginal decline |
| Export Prices | First decline in nearly a year |
| Business Confidence | Nine-month low |
Key Takeaways
- Manufacturing expansion sustained: PMI Manufacturing edged down from 52.1 to 52.0, extending the expansionary streak to 11 consecutive months, the longest since mid‑2021.
- Production gained momentum: Output expanded at its fastest pace since April, supported by solid new orders and continued export growth. Purchasing activity accelerated as firms responded to higher workloads.
- Capacity pressures persisted: Employment increased only marginally, while backlogs accumulated for a ninth consecutive month despite stronger production.
- Pricing weakness contrasted with stronger activity: Intense competition pushed factory‑gate prices lower for the second time in three months, while input costs continued rising at a slower pace.
- Business confidence softened: Future output optimism fell to a nine‑month low amid concerns about elevated input costs and competition, suggesting that stronger production has yet to translate into a more favorable business outlook.
Also Read
- XRPL RLUSD Supply Drops 29% as Key XRP Trading Pool Reserves Remain Stable
- Japan’s Manufacturing PMI Edges Down to 53.3 as Growth Moderates, Capacity Pressures Continue
- Weekly Earnings Preview: Apple, AMD, Palantir, Arm, McDonald’s, and Uber to Report Key Results
- Cardano’s 2027 Budget Proposal Balances Institutional Stewardship with Direct Grant Access


