






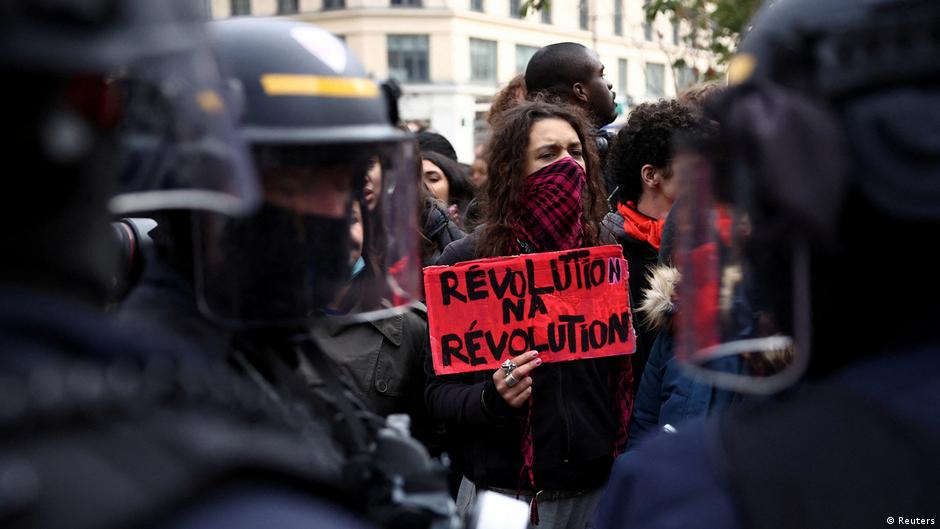
Heavily indebted, politically stuck in a stalemate between opposing extremes and led by a government lacking a parliamentary majority, France finds itself in a defining predicament.
In reaction to nationwide protests, the government proposes €4 billion in low‑interest loans for school renovations by 2030 and an extra €1 billion for universities by 2029, yet such spending promises funds the state does not possess.
France’s public debt totals about 120 % of its GDP, while Germany’s debt‑to‑GDP ratio sits near 65 % despite Berlin’s €600 billion infrastructure and defence investment package.
Germany retains a top‑rating AAA credit score. By contrast, France holds AA, A+ or Aa3 ratings depending on the agency, and its outlook is viewed as negative by several firms, whereas Germany’s outlook stays stable.
Consequently, France must borrow at higher rates than Germany. The spread over German Bunds—the risk premium—is at its highest since the financial crisis, with France paying roughly 1.6 percentage points more on ten‑year bonds.
A barometer of France’s public finances
The spread serves as a “fever gauge” for bond markets, said Friedrich Heinemann, an economist at the Leibniz Centre for European Economic Research (ZEW) in Mannheim.
“When this fever gauge spikes, it forces a course correction. If the spread climbs sharply, France’s financing conditions tighten, pushing up borrowing costs for individuals and businesses. Banks then face strain, and the crisis deepens,” Heinemann told DW.
“Such a scenario could slide into a full‑blown financial crisis, delivering a stark warning that the current path cannot continue without risking a genuine economic collapse,” he added.
Echoes of eurozone crisis
France’s premium last reached comparable heights at the close of 2011 during the eurozone debt crisis. Strikingly, the spread over German Bunds has more than doubled since June 2026.
The primary driver is not overall interest rates but the rising risk premium investors demand due to high debt, political instability, large budget deficits and recent unrest.
Higher rates expand the portion of the national budget needed for debt servicing. France is forecast to spend over €79 billion on interest payments in 2026, more than €91 billion in 2027 and possibly €125‑132 billion by 2030.
These totals encompass payments by social‑security systems and local governments. The central government’s interest bill alone is now estimated at €62.6 billion by the Agence France Trésor.
In the coming years France will need to refinance sizable volumes of bonds issued when rates were historically low, while its sizable budget deficit forces it to incur fresh borrowing.
Warning shot for Germany
Rising borrowing costs are also weighing on Germany. ZEW economist Heinemann projects that German interest payments will surge markedly by the early 2030s.
“For the federal government alone, which has so far spent about €30 billion, the cost will triple within a few years as debt and rates climb. It will not stop there; the outlay will surpass €90 billion, and an annual interest bill of €100 billion is not far off,” the economist warned.
Could France’s debt crisis become a problem for Europe?
To view this video please enable JavaScript, and consider upgrading to a web browser that supports HTML5 video
In France, economic realities appear to have little sway over political debate. Both the far‑right National Rally (RN) and the far‑left La France Insoumise (LFI) are campaigning on expensive promises.
RN leader Marine Le Pen proposes restoring the retirement age to 62 while touting €140 billion in savings. Jean‑Luc Mélenchon, LFI’s leader, has suggested burning government bonds held by the French central bank.
“Nobody will ever notice they’ve vanished,” he asserted.
‘Fairy tales from the left and the right’
Heinemann regards this as “a textbook case of radical parties on both the right and the left peddling economic fairy tales.”
Their shared message, he said, is that “there is a way out of this mess without fiscal consolidation or painful cuts.”
Charrier remains convinced that many French citizens have yet to grasp the gravity of the situation.
“The euro has facilitated cheap financing for France and long softened adjustment pressure,” he noted.
“Historically, devaluations of the franc instantly transmitted imbalances through falling purchasing power and higher prices. Today that warning signal is absent, creating the illusion that needed adjustments can be delayed indefinitely,” Charrier observed.
This article was originally written in German.


