



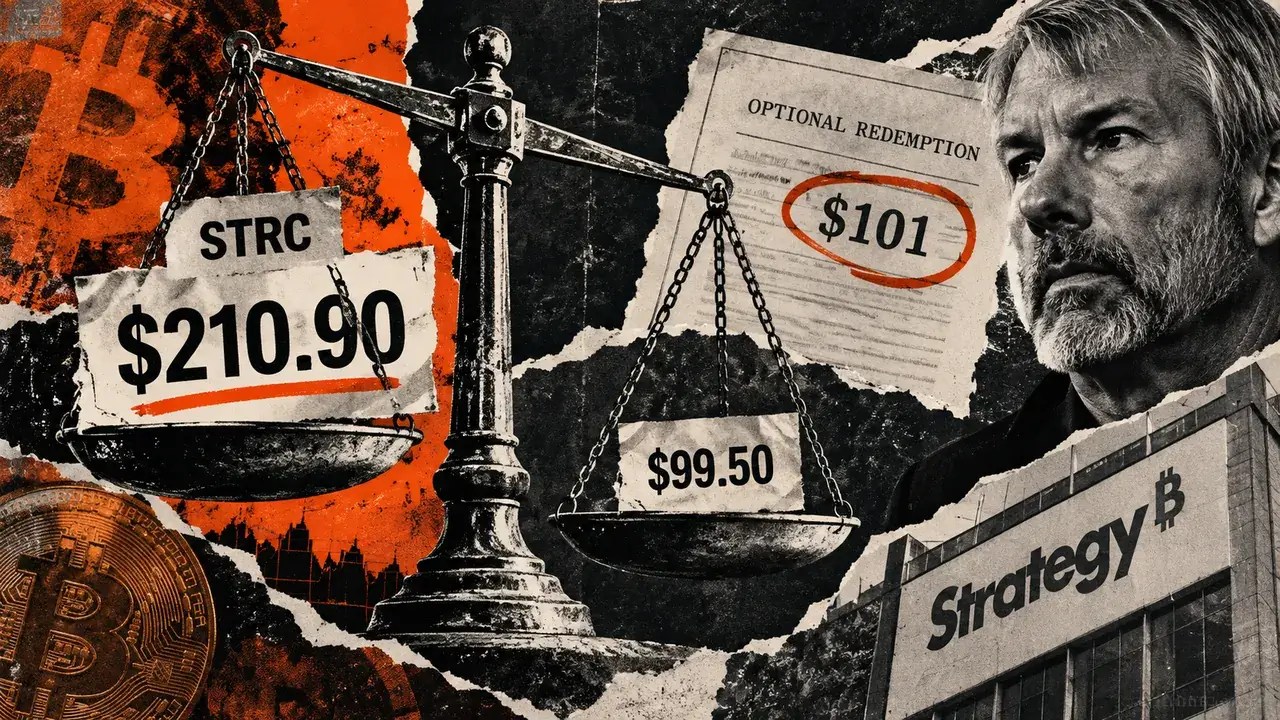
Strategy’s Bitcoin credit calculator generated an illustrative STRC price of $210.90 on October 2, while displaying a market-price input of $99.50 for the perpetual preferred stock. Additionally, the issuer retains the option to redeem shares at $101, or at a higher amount of its choosing, plus any applicable unpaid dividends.
This discrepancy highlights the inherent limitations of the calculator’s model. The published formula maintains the current dividend as a constant while substituting the market’s actual credit spread with a modeled Bitcoin spread. It does not explicitly value the issuer’s call option or account for potential future dividend resets. Strategy’s pricing dashboard separately discloses these features, warning that the call option can cause the derived price to diverge significantly from realizable market prices.
For prospective buyers, the calculation represents a theoretical view of the security under specific assumptions. It does not establish that STRC is actually worth more than twice its displayed market price, nor does it guarantee that a holder can realize either the model output or the redemption amount on demand.
How the Calculator Reaches $210.90
At approximately 08:18 UTC on October 2, the dashboard utilized a Bitcoin price input of $86,593, an assumed annual return of 10%, and a volatility of 40%. The STRC row displayed a 12.06% effective yield, a 5.23% risk-free yield, and 46 basis points of BTC Credit, which represents Strategy’s modeled credit spread.
The published pricing formula divides the annual dividend by the sum of the risk-free yield and BTC Credit. Applying a $12 annual dividend alongside the displayed inputs yields the following:
$12 ÷ (5.23% + 0.46%) ≈ $210.90.
This arithmetic reproduces the rounded output. The row’s actual market spread—the extra yield above the risk-free rate represented by the displayed market price—was 684 basis points. BTC Credit is the model’s estimate of that credit spread. Substituting 46 basis points for the much larger market spread lowers the formula’s discount rate and consequently raises its output. Because the yield inputs are rounded, they need not reproduce the displayed market spread exactly.
The formula makes the underlying economic mechanism transparent. Holding other inputs constant, a larger dividend increases the numerator, while a smaller modeled spread decreases the denominator. Utilizing a high current dividend alongside a significantly smaller modeled spread can produce a large illustrative price, without altering the actual rights held by the shareholders.
Strategy expressly states that the output is neither a fair-value determination nor a price target. Its assumptions include full scheduled payments and a simplified treatment of Bitcoin coverage and claims. The dashboard also warns that displayed market prices may be stale and do not constitute executable quotes. These figures represent a dated snapshot, and Bitcoin-linked model inputs are subject to change after observation.
Consequently, the output cannot explain why the market price differs from the calculation. Issuer options, payment risk, trading conditions, and the model’s assumptions all influence the comparison; the entire gap cannot be attributed solely to the call right.
Under STRC’s amended certificate of designations, Strategy can elect optional redemption at $101 per share or a higher amount it announces. Applicable accumulated unpaid dividends and compounding are added, with adjustments for declared dividends payable separately to record holders.
A partial optional redemption must leave at least $250 million of stated amount outstanding and uncalled when notice is provided. The redemption date follows the notice by between three business days and 60 calendar days. These terms govern an issuer action, rather than an ordinary holder right to cash out.
If Strategy exercises this option, the holder receives the contractual redemption payment instead of continuing to own the dividend-paying share. This possibility is critical when interpreting a calculation that capitalizes the current dividend without explicitly valuing the call option.
However, the $101 figure neither promises a redemption nor imposes an absolute secondary-market price ceiling. Strategy can choose not to call, and the certificate permits a higher announced amount. Furthermore, a buyer cannot assume the company will redeem the shares merely because STRC trades below that level.
The three prices describe different things: $99.50 is the dashboard’s market input, $210.90 is an assumption-driven output, and $101 plus applicable dividends is a potential issuer-selected redemption payment. Each comes with different conditions.

The numerator is adjustable as well. STRC’s current rate does not promise the same cash income indefinitely.
For each monthly reference period, ordinary rate reductions are constrained by a 25-basis-point allowance plus specified declines in the one-month term SOFR, a SOFR floor, and conditions covering prior accumulated dividends. Those dividends must be paid, or fully declared with sufficient consideration set aside. While these restrictions limit discretion, they do not eliminate it.
STRC dividends accumulate cumulatively. However, cash payment still requires board declaration and legally available funds. An accumulated entitlement and cash received on a particular date are distinct considerations for anyone relying on that income.
The payment calendar has already deviated from the monthly schedule described in the July 2025 offering announcement. The amended certificate, effective June 30, 2026, established twice-monthly payments while retaining monthly reference periods for rate resets.
Strategy’s October 1 filing reports that its September 30 action maintained the 12% annual rate for periods beginning October 16 and declared a $0.50 payment for the semi-monthly period ending October 31.
The daily-dividend proposal awaits an October 28 shareholder vote. If approved and adopted on time, with dividends declared by the board, the planned first daily record date is November 1 and the first payment is November 2. Payments would follow record dates on the next business day.
More frequent payments would alter when income arrives. However, they would not create a daily redemption right, lock in the dividend rate, or guarantee principal stability.
Bitcoin Coverage Does Not Replace Dollar Capacity
Strategy’s Bitcoin holdings and its cash-payment resources address separate questions. Bitcoin coverage concerns assets relative to claims under the model’s assumptions. Dividends payable in dollars, however, require dollar capacity when payment comes due.
In its September 28 reserve update, Strategy reported a $5.02 billion USD Reserve and a separate $1.00 billion USD Cash balance as of September 27. The reserve supports preferred dividends and debt interest, while USD Cash serves broader treasury and capital-allocation purposes.
During September 21–27, the company used $22.1 million of the reserve for preferred dividends and $48.1 million of USD Cash to help fund STRC repurchases. These are dated balances and uses, rather than a guarantee of future payment coverage. The broader cash pool should not be treated as interchangeable with the designated reserve.
Claim priority also matters. Debt and STRF sit above STRC, while STRK, STRE, and STRD are junior preferred claims. Bitcoin is not pledged directly to STRC holders, and additional senior claims or other liabilities can affect the assets available to them.
Michael Saylor’s September 29 explanation of digital credit describes Bitcoin capital and dollar liquidity as distinct parts of the structure. He presents reserve management, financing, and discretionary repurchases as tools, while stating that repurchases do not guarantee a price floor. These are management choices and objectives, rather than assurances embedded in the calculator.
Earlier CryptoSlate coverage examined third-party dividend-durability modeling and Strategy’s buyback allocation. The issuer’s own price formula adds a narrower question: how much can buyers learn from replacing one spread while holding other inputs constant?
The answer is bounded by what the formula includes. Changes in the declared rate alter the income being capitalized; a call changes how long a holder owns that income stream; reserve decisions and senior claims affect payment capacity. At the October 2 snapshot, the calculator’s large gap to the displayed market price resolved none of those contractual and payment questions.
Also Read
- Rupee Weakness Prompts Record $18.34 Billion Dip in India’s Forex Reserves
- Doctor Profit Exits XRP, Citing Excessive Speculation and Market Risk
- Forward Industries’ $1 Billion Solana Accumulation Puts $150 Price Target in Play
- Ciena Jumps Nearly 8% on Record AI Optical Demand and Raised Fiscal Guidance