







The US two-year yield has already surged past key resistance levels, signaling a broader Federal Reserve tightening cycle, yet the Dollar has failed to follow suit. This week’s Federal Open Market Committee decision and Summary of Economic Projections will determine whether the central bank validates the rate path implied by the bond market or if the currency remains tethered by hesitation.
The Yield–Dollar Divergence
One market has already voted for a more aggressive Fed tightening trajectory. The US two-year yield shattered medium-term resistance last week, accelerating to approximately 4.63%. Meanwhile, the Dollar index remains range-bound between support at 98.55–98.67 and resistance at 99.86, highlighting a clear disconnect between US rate expectations and the currency poised to benefit from them.
The upcoming FOMC decision will likely dictate whether this gap closes. A hawkish set of rate projections would provide the Dollar with the relative policy advantage necessary to track yields higher. Conversely, if the projections merely confirm the widely expected Wednesday hike, they might expose just how much tightening the market has already priced in. As the index approaches a critical technical juncture, the outcome will likely define its next medium-term trend and shape the Dollar’s trajectory through the remainder of 2026.
The Hike Is Already Priced
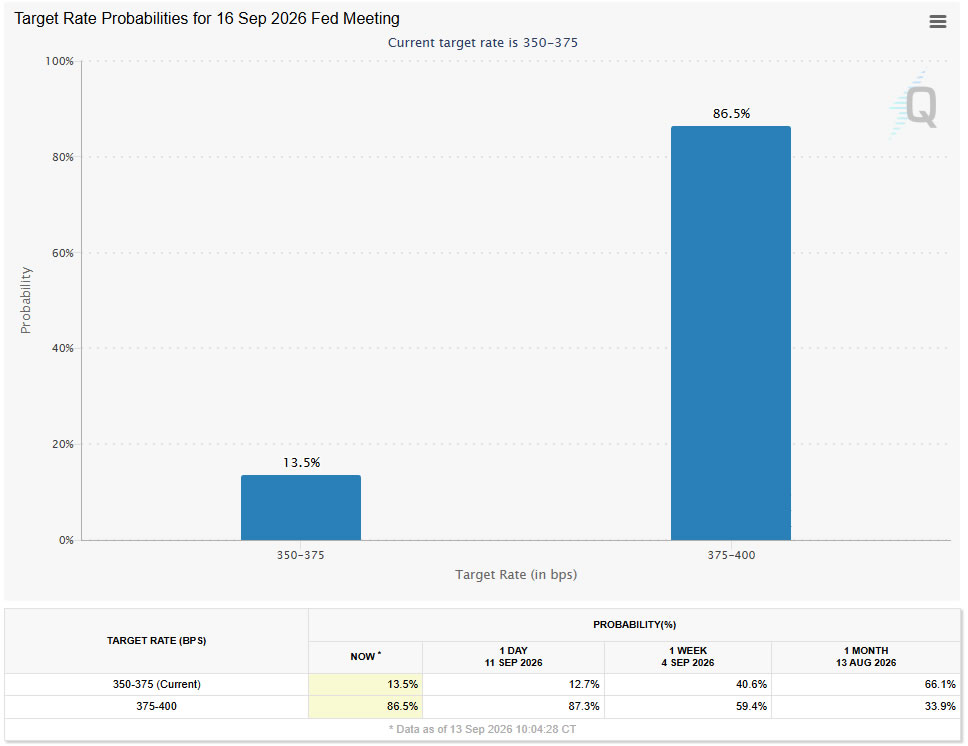
The September rate decision itself is no longer the primary source of uncertainty. CME FedWatch placed the probability of a 25 basis point hike to 3.75–4.00% at 86.5% on September 13, a sharp increase from 59.4% a week prior and 33.9% a month earlier. Prediction markets independently estimated the likelihood in the high-70s to high-80s, reflecting broad consensus across venues.
At these levels, an increase would largely formalize a move the market has already anticipated. A hold would constitute the true policy surprise. Assuming the Fed raises rates as expected, the more consequential information will stem from the Summary of Economic Projections, specifically whether officials validate the additional tightening currently embedded in the futures curve.

Warsh’s Missing Dot Is the Base Case
Federal Reserve Chair Kevin Warsh declined to submit an individual rate projection at his first meeting as Chair in June, breaking with a practice followed by Fed chairs since individual projections were introduced. He cited his longstanding opposition to personal rate forecasts and forward guidance.
Warsh withholding his projection again should therefore be treated as the base case rather than a fresh dovish or hawkish signal. The more critical procedural question is whether any other officials follow his lead. Further abstentions would reduce the total number of projections, making shifts in the median noisier and increasing the importance of checking the participation count before drawing conclusions from a minor fluctuation.
The Median Dot Is the Real Test
The June projections showed a committee already leaning toward tighter policy. Excluding Warsh, nine of 18 participants expected at least one hike by the end of 2026, eight anticipated rates to remain unchanged, and one projected a cut. The median year-end projection rose from 3.4% in March to 3.8% in June. No participant had projected a 2026 hike in March.
A 3.8% median was broadly consistent with the single increase now expected this week. If the year-end median remains around that level, the projections would point toward a one-and-done outcome, even if the accompanying statement retains flexibility. A move above the new 3.75–4.00% target range would indicate the committee itself expects another increase at either the October 28 or December 9 meeting.
The distribution around the median will matter as much as the median itself. Three officials dissented in favor of a hike in July, up from two in June, demonstrating that the committee’s hawkish wing was already expanding before the latest inflation and energy developments. The 2027 dots will also indicate whether officials view a limited 2026 adjustment or the beginning of a longer tightening cycle.
Markets Have Moved Faster Than the Fed
At the end of August, the futures curve was still centered around approximately two cumulative hikes, with probabilities falling away quickly beyond that point. Pricing has since extended materially further. By December 2027, 4.50–4.75% is now the narrowly modal range at 27.8%, followed closely by 4.25–4.50% at 27.5%. The 4.75–5.00% range carries another 16.5%, while rates of 5.00% or higher retain a combined probability of 6.9%.
The repricing is not confined to the distant path. Markets assign a 40.2% probability that a second cumulative hike will arrive as soon as October. By December, two cumulative increases are the modal outcome at 48.3%, with a further 26.2% probability of three hikes by then.


That shift followed a concentrated sequence of inflationary signals. Warsh used his Jackson Hole speech to stress that the 2% inflation target was fixed and that inflation needed to move toward it at sufficient speed. August payrolls then exceeded expectations, PPI inflation accelerated to 5.4% year on year, and core CPI rose 0.3% month on month, against expectations of 0.2%. Shelter inflation reaccelerated from 0.1% to 0.3%, while gasoline accounted for more than one-third of the monthly headline increase.
Oil supplied the latest push. Brent approached $110 last week as the proposed Salalah talks on a temporary Hormuz shipping corridor were postponed, Saudi Arabia’s East–West pipeline stayed closed following drone strikes, and Houthi advances intensified concerns surrounding Bab el-Mandeb. The renewed energy shock added another potential source of inflation persistence just as markets were assessing whether the Fed needed to tighten more aggressively.
Why the Dollar Hasn’t Followed
The Dollar’s hesitation reflects three separate mechanisms.
First, the Fed has provided relatively little guidance under Warsh. Markets have constructed a more aggressive path based on incoming data and energy prices rather than a clear change in the Fed’s communicated reaction function. This makes the repricing more vulnerable to an SEP that fails to endorse the curve.
Second, the quality of the yield rise matters. Higher yields driven by stronger US growth and an independently hawkish Fed would normally provide direct support for the Dollar. Yields rising partly because of an external oil shock create a less straightforward signal, as the same shock can weaken growth, raise inflation abroad, and produce tightening expectations across several economies.
Third, the global policy backdrop has become less supportive of exclusive Dollar strength. The ECB had already raised rates twice this year, while markets also expect further BoJ tightening. Higher US yields therefore represent a rise in absolute returns, but not necessarily a comparable improvement in the relative US policy advantage.
The FOMC must therefore do more than deliver the expected increase. It must demonstrate that the US tightening path is moving far ahead of other central banks to turn higher Treasury yields into sustained Dollar demand.
ActionForex’s Technical View on the US Two-Year Yield: Confirming the Repricing
The US two-year yield surged through 4.424% and 4.527% last week and reached the medium-term resistance area around 4.628%. The move strengthens the case that the correction from the 5.259% high in 2023 completed as a triangle at 3.365%.

Further upside is favored while 4.370% resistance-turned-support holds. The next projection target stands at 4.791%. Overbought conditions in the daily RSI could cap the initial attempt, but a sustained break would bring the 5.259% high back into view and raise the possibility that the longer-term uptrend is resuming.
That structure shows the rates market has moved beyond pricing a single September increase. The question is whether the Fed’s projections confirm the broader tightening path now implied by the breakout.

ActionForex’s Technical View on DXY: Still Needs 99.86
DXY defended the 50% retracement of the rise from 95.55 to 101.80, at 98.67, for a second time last week and recovered. However, the rebound is still capped below 99.86 resistance and the falling 55-day EMA. Unlike the US two-year yield, the Dollar hasn’t confirmed a bullish medium-term reversal.
A decisive break above 99.86 would argue that the pullback from 101.80 has completed and open a return to that resistance. Such a move would show the FOMC had finally converted higher US yields into a stronger relative policy advantage.
Risk stays tilted lower while 99.86 holds. A firm break below 98.55 would extend the fall from 101.80 toward the 61.8% retracement at 97.93 and then 97.62 support. That outcome would reinforce the message that higher Treasury yields alone are insufficient to unlock the Dollar.
Three Possible FOMC Verdicts
The clearest bullish scenario would combine the expected hike with an upward shift in the year-end median showing officials anticipate another increase in October or December. Broader upward movement in the 2027 projections would strengthen the signal. A break above 99.86 would then confirm the Dollar is closing the gap with the rates market and target a return to 101.80.
The bearish scenario would see the Fed hike but project little beyond it. An unchanged year-end median, reduced participation, and limited guidance from Warsh would leave the curve ahead of the committee and create a classic sell-the-fact risk. A break below 98.55 would expose 97.93 and 97.62, while the overbought US two-year yield could begin to unwind.
A third outcome would preserve the divergence. The Fed could validate further tightening without creating a sufficiently distinct US rate advantage over other central banks. US yields could then stay elevated while DXY remains confined below 99.86.
The hike is priced. The unresolved question is whether the Fed can validate enough of the path beyond it to make the Dollar follow. The answer at 98.55 or 99.86 could set the currency’s direction through year-end.
Key Takeaways
- September’s 25bp hike is now priced at 86.5% and is largely a formality; the real signal comes from the Summary of Economic Projections and whether the year-end median rises above 3.8%.
- Markets already price roughly two cumulative hikes by year-end and have extended pricing further out to 2027, well ahead of what the Fed’s own June projections implied.
- The Dollar’s failure to follow the two-year yield’s breakout reflects three factors: limited Fed guidance under Warsh, yields rising partly from an oil shock rather than pure Fed hawkishness, and a less exclusive US rate advantage as the ECB and BoJ also tighten.
- The US two-year yield has broken toward 4.791% resistance, while DXY remains capped below 99.86 and above 98.55, needing the FOMC to validate a broader tightening path to break out.
- Three FOMC outcomes are in play: a bullish scenario (hike plus a higher median, opening 101.80), a bearish sell-the-fact scenario (hike with no further guidance, opening 97.93-97.62), or a persistent divergence where yields stay elevated without lifting the Dollar.


