







The September ISM Services PMI slipped to 54.9, just below the 55.3 consensus forecast, yet it remained comfortably above the 50‑point threshold that separates expansion from contraction. The slowdown was driven mainly by softer business activity and new orders, with the Business Activity Index easing from 61.7 to 56.5 and New Orders pulling back from 60.9 to 59.8. Despite the moderation, both sub‑indices continue to signal solid underlying momentum in the services sector.
Labour market conditions showed a notable reversal, as the Employment Index rebounded from 47.8 to 50.1, re‑entering expansion after three months of contraction. Meanwhile, price pressures accelerated sharply, with the Prices Paid Index climbing from 72.6 to 74.0—the highest level since July 2022. Supplier delivery times lengthened, moving the Supplier Deliveries index up to 53.2, and backlogs of orders grew modestly to 56.6. Survey respondents identified tariffs and, especially, fuel costs as the primary supply‑chain concerns, with fuel‑related issues cited roughly twice as often as any other single factor.
External demand softened markedly, as New Export Orders plunged from 56.3 to 46.9, slipping back into contraction, while Imports slowed to 52.9. The overall picture points to a services economy that is losing some momentum but remains firmly expansionary, supported by a stabilizing jobs market and heightened inflationary pressure. The mixed internals suggest that the softer headline figure masks a more nuanced reality.
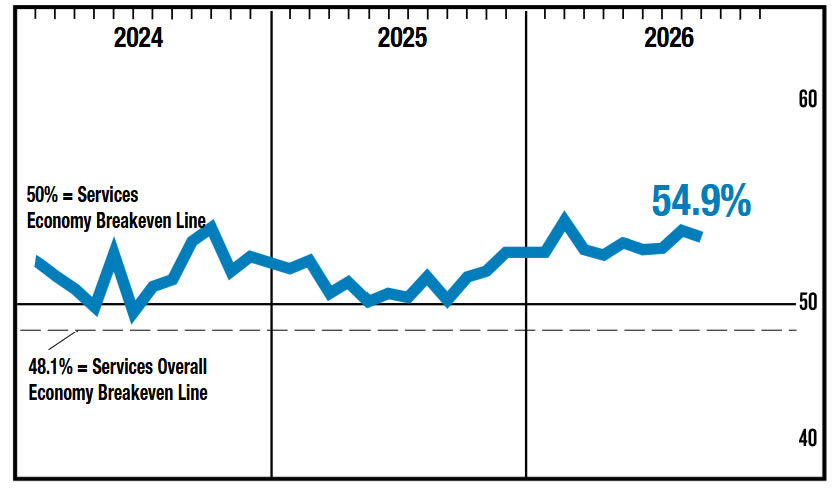

Data Summary
Indicator
Sep
Aug
ISM Services PMI
54.9
55.4
Business Activity
56.5
61.7
New Orders
59.8
60.9
Employment
50.1
47.8
Prices Paid
74.0
72.6
New Export Orders
46.9
56.3
Key Takeaways
- Services growth moderated: ISM Services PMI fell to 54.9, slightly below the 55.3 consensus but remaining in expansion territory.
- Activity cooled from strong levels: Business Activity dropped to 56.5 and New Orders eased to 59.8.
- Employment recovered: The Employment Index rose to 50.1, re‑entering expansion after three months below 50.
- Price pressure intensified: Prices Paid climbed to 74.0, the highest reading since July 2022.
- Supply conditions tightened: Supplier Deliveries rose to 53.2 and Backlog of Orders increased to 56.6.
- Fuel costs and tariffs dominate cost concerns: Survey respondents flagged these issues as the main supply‑chain pressures.
- External demand weakened sharply: New Export Orders fell to 46.9, moving into contraction.
- Overall, the report shows slower but still solid services growth, a stabilizing jobs market, and stronger inflation pressure, indicating that the softer headline masks more resilient internals.
Also Read
- Metaplanet Executes Bitcoin Sale and Repurchase to Demonstrate Liquidity for Credit Rating
- Bitcoin’s Dual Golden Cross Signals Strengthening Momentum Amid Favorable Macro Shift
- GBPJPY Wave Analysis: Bullish Reversal Targets 210.00
- ICE and OKX File for 24/7 Tokenized Equities Trading via Uniswap on X Layer


